What NJ Homeowners Need to Know About Rising Home Insurance Costs
Why is my homeowners insurance so expensive in New Jersey?
If you’ve opened your homeowners insurance renewal recently and noticed your premium has increased, you’re not alone. Many New Jersey homeowners are asking the same question.
Even if you haven’t filed a claim, haven’t made major changes to your home, and haven’t had any recent problems, your homeowners insurance premium can still increase.
So what’s causing New Jersey home insurance rates to rise?
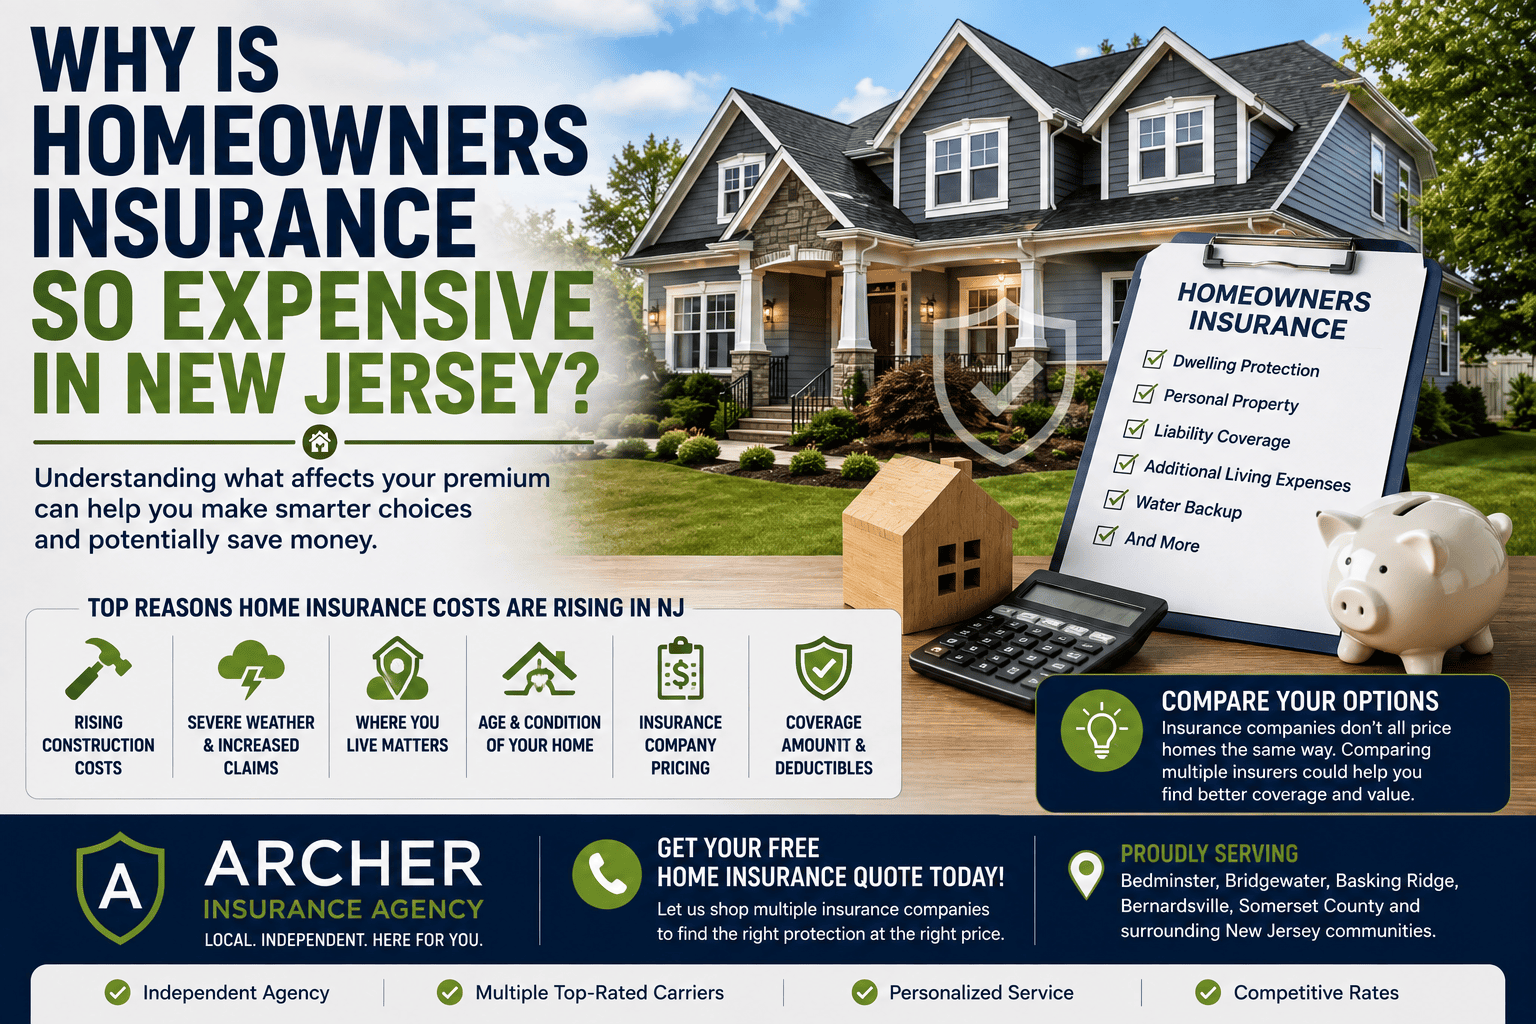
Several factors can affect the cost of homeowners insurance, including construction costs, weather-related claims, insurance company pricing, the location and characteristics of your home, and the coverage you choose.
The good news is that you don’t necessarily have to accept your renewal price without comparing your options.
At Archer Insurance Agency, we help homeowners in Bedminster, Somerset County, Basking Ridge, Bernardsville, Bridgewater, and surrounding New Jersey communities compare homeowners insurance from multiple insurance companies.
Why Has My Homeowners Insurance Gone Up If I Didn’t File a Claim?
This is one of the most common questions homeowners ask:
“I’ve never filed a claim. Why did my homeowners insurance go up?”
Your individual claim history is only one factor that can affect your premium.
Insurance companies also consider the overall cost of paying claims across their book of business.
When insurers experience higher claim costs, they may adjust premiums to reflect changing risk and expenses.
That means your premium can increase even if you personally have never filed a homeowners insurance claim.
Are Construction Costs Making NJ Home Insurance More Expensive?
Yes, construction costs can have a significant impact on homeowners insurance.
If your home were seriously damaged or destroyed, the insurance company may need to pay contractors for labor and materials to repair or rebuild it, subject to your policy.
The cost of:
-
Lumber
-
Roofing materials
-
Windows
-
Electrical work
-
Plumbing
-
Building materials
-
Contractor labor
can change over time.
If the estimated cost to rebuild homes increases, insurance companies may need to account for those higher potential claim costs.
This is one reason it’s important to regularly review your dwelling coverage and replacement cost estimate.
Does the Age of My Roof Affect My Home Insurance Premium?
It can.
Your roof is one of the most important components of your home from an insurance perspective.
The age, condition, type, and construction of your roof can affect how an insurance company evaluates your property.
Older roofs may also create underwriting challenges with some insurance companies.
If you’ve recently replaced your roof, make sure your insurance company has the updated information.
A roof replacement doesn’t guarantee a lower premium, but it can be an important factor when an insurance company evaluates your home.
Does Where I Live in New Jersey Affect My Home Insurance Cost?
Yes.
Insurance companies consider the characteristics of the area where your home is located when determining rates.
Factors can include:
-
Local claims history
-
Weather exposure
-
Property characteristics
-
Fire protection
-
Crime and theft trends
-
Cost of repairs
-
Other location-specific risks
This means two homeowners with very similar houses can pay different amounts for homeowners insurance depending on where the properties are located.
Are Severe Storms Increasing Home Insurance Costs in NJ?
Weather-related claims are an important consideration for homeowners insurance companies.
New Jersey homeowners can experience:
-
Severe thunderstorms
-
High winds
-
Hail
-
Heavy rain
-
Winter storms
-
Fallen trees
-
Other weather-related damage
When severe weather causes large numbers of claims, insurance companies can face substantial losses.
Those broader claims costs can influence insurance pricing.
Why Are Some NJ Homeowners Having Trouble Finding Insurance?
Another issue New Jersey homeowners are increasingly encountering is insurance company underwriting restrictions.
Insurance companies may have guidelines regarding:
-
Roof age
-
Electrical systems
-
Plumbing
-
Heating systems
-
Prior claims
-
Property condition
-
Swimming pools
-
Trampolines
-
Certain types of construction
-
Other property characteristics
A home that one insurance company considers acceptable may not fit another company’s underwriting guidelines.
That’s one of the biggest advantages of working with an independent insurance agency.
Instead of contacting companies one at a time, you can have an agency compare available options for you.
Can Raising My Deductible Lower My Home Insurance Premium?
Potentially.
Your deductible is the amount you are generally responsible for paying toward a covered claim before insurance responds, subject to the policy.
A higher deductible can sometimes result in a lower premium.
However, you shouldn’t choose a deductible simply because it produces the lowest insurance price.
Ask yourself:
“If I had a covered claim tomorrow, could I comfortably afford this deductible?”
The right deductible depends on your financial situation and comfort level.
Can Bundling Home and Auto Insurance Save Money?
It can.
Many insurance companies offer multi-policy discounts when you insure your home and auto policies with the same carrier.
Bundling may provide:
-
A multi-policy discount
-
Simplified billing
-
One insurance company for multiple policies
-
Easier policy management
However, don’t assume that your current insurance company automatically offers the best price for both policies.
Comparing multiple carriers can help determine whether switching or bundling could save you money.
Can I Lower My Homeowners Insurance Premium Without Reducing Coverage?
There may be several ways to potentially reduce your premium without simply cutting important coverage.
Ask your insurance agent about:
Reviewing Your Deductible
A different deductible may change your premium.
Checking Available Discounts
Depending on the insurance company, you may qualify for discounts related to:
-
Home and auto bundling
-
Alarm systems
-
Newer homes
-
Roof updates
-
Claims history
-
Other qualifying features
Reviewing Your Coverage
Your home and personal property can change over time.
You may have coverage that no longer reflects your current situation—or you may have new exposures that require additional protection.
Comparing Insurance Companies
This may be the most important step.
Insurance companies don’t all price the same home the same way.
Should I Shop Around for Homeowners Insurance Every Year?
You don’t necessarily need to switch insurance companies every year.
But it can be worthwhile to review your homeowners insurance regularly, especially when your premium increases significantly.
A policy review can help you determine:
-
Whether your coverage is still appropriate
-
Whether your replacement cost estimate needs updating
-
Whether you qualify for discounts
-
Whether your deductible still makes sense
-
Whether another insurance company may offer a better combination of price and coverage
And you don’t have to do all the shopping yourself.
Why Use an Independent Insurance Agency in New Jersey?
When you contact a captive insurance agent, you’re generally working with one insurance company.
An independent insurance agency can represent multiple insurance carriers.
That means Archer Insurance Agency can compare different companies based on your home’s characteristics and your coverage needs.
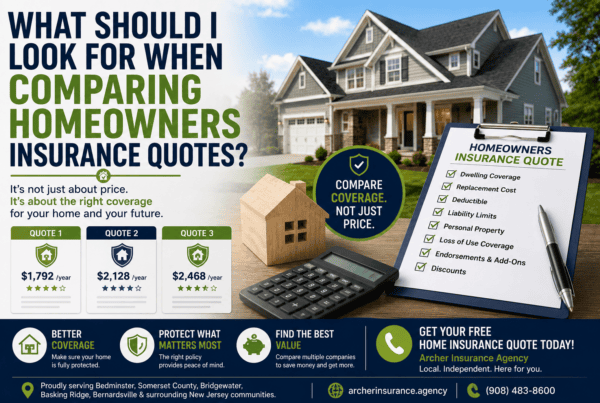
We help homeowners compare:
-
Homeowners insurance premiums
-
Dwelling coverage
-
Replacement cost
-
Deductibles
-
Liability limits
-
Personal property coverage
-
Water backup coverage
-
Other available endorsements
-
Home and auto bundle options
The goal isn’t simply to find the cheapest homeowners insurance.
It’s to find competitive pricing while maintaining appropriate coverage.
Is It Time to Compare Your New Jersey Home Insurance?
If your homeowners insurance premium has increased significantly, don’t automatically assume you have to accept the new price.
Your current insurance company may still be your best option—but you won’t know until you compare.
At Archer Insurance Agency, we can shop multiple insurance companies on your behalf.
We serve homeowners throughout Bedminster, Bridgewater, Basking Ridge, Bernardsville, Somerset County, and surrounding New Jersey communities.
🏠 Get Your Free Home Insurance Quote
Has your NJ homeowners insurance premium increased?
Let Archer Insurance Agency compare your current coverage with options from multiple insurance companies.
We’ll review your policy, explain your coverage, and help you determine whether there may be a better combination of price and protection available.
Don’t just renew—compare your options.
Contact Archer Insurance Agency today for a free, no-obligation New Jersey homeowners insurance quote.
Local. Independent. Here for you.